Crusoe Valuation History: A Deep Dive Into the AI Factory Company Before Its IPO
Crusoe's valuation went from $1.75B (Series C, 2022) to $30.9B (Series F, September 2026). Every confirmed round with sources, revenue estimates, Stargate and IPO status.
Key facts
- On September 17, 2026, Crusoe announced the initial close of an anticipated $3.9 billion Series F at a $30.9 billion post-money valuation, co-led by Atreides Management, Mubadala Capital and Valor Equity Partners.
- Crusoe's Form D filing of September 17, 2026, shows $3.1 billion of the $3.9 billion offering sold.
- Crusoe's valuation rose about 18-fold from $1.75 billion after its April 2022 Series C and roughly tripled from the more than $10 billion of its October 2025 Series E.
- In September 2026, Crusoe reported more than 6 GW of contracted capacity, 1 GW in operation and more than $140 billion in total contracted value.
- As of October 21, 2026, Crusoe had not publicly filed an S-1: SEC EDGAR lists only Form D notices for the company.
Contents
- What does Crusoe do?
- How has Crusoe's valuation changed since 2022?
- Why did Crusoe's valuation triple in 2026?
- What is known about Crusoe's revenue?
- What role do Stargate and Abilene play?
- How does Crusoe compare with CoreWeave?
- When could Crusoe go public?
- What are the risks?
- Frequently asked questions
- What is Crusoe's latest valuation?
- Has Crusoe filed for an IPO?
- Does Crusoe disclose its revenue?
Crusoe's valuation history runs from $1.75 billion in its April 2022 Series C to $30.9 billion post-money in its Series F, whose initial close the company announced on September 17, 2026. In between came a $2.8 billion Series D in December 2024 and a Series E above $10 billion in October 2025. The Denver-based AI infrastructure company has not yet filed for an IPO.
What does Crusoe do?
Crusoe calls itself an AI factory company: it secures power, builds data centers and rents out GPU computing through its own cloud. One company covers the chain from the energy source to the customer's AI model.
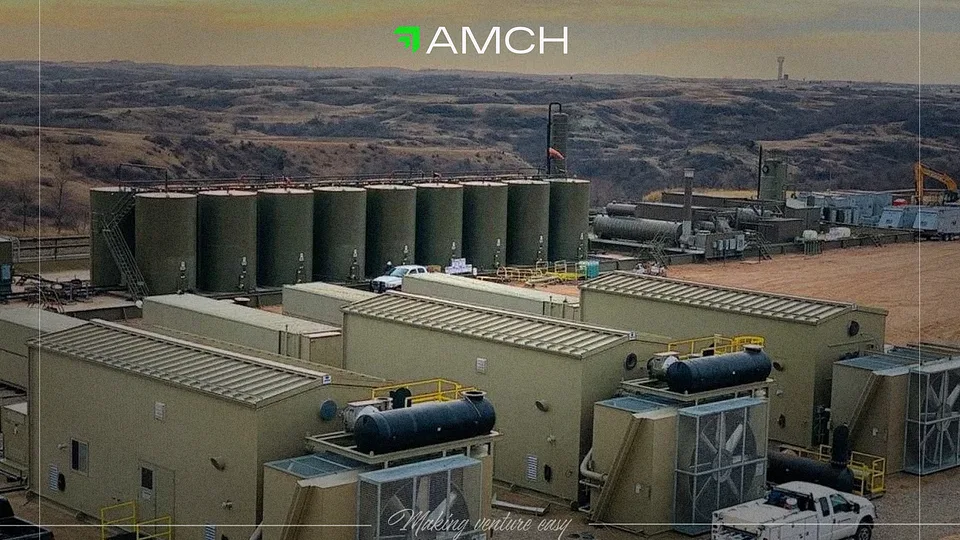
Energy. Chase Lochmiller and Cully Cavness founded Crusoe in 2018 to power modular data centers at oil fields with gas that would otherwise be flared, and used that computing for bitcoin mining. In March 2025 Crusoe agreed to sell the mining business to NYDIG and turned fully to AI. In October 2025 it put its power pipeline at more than 45 GW, with partners including Tallgrass, Redwood Materials and Lancium.
Data centers. The flagship is a 1.2 GW campus in Abilene, Texas, covered in the Stargate section below. Smaller sites test other models: in March 2026 Crusoe and Redwood Materials agreed to expand their campus in Sparks, Nevada, from 4 to 24 modular Crusoe Spark data centers, nearly seven times the original compute. Its solar-and-battery microgrid ran at 99.2% availability over seven months.
Cloud. Crusoe Cloud, generally available since December 2024, rents GPU capacity for AI training and inference. Crusoe has named Cursor, Decart, Fireworks, Odyssey and Together AI among its cloud customers, and TechCrunch lists Meta, Microsoft and Oracle as customers. SemiAnalysis gave Crusoe Cloud a Gold rating in its ClusterMAX ratings of GPU clouds in 2025, and Fast Company ranked Crusoe third in Computing on its 2026 list of the most innovative companies.
How has Crusoe's valuation changed since 2022?
It grew about 18-fold from the Series C to the Series F, and most of that came in the last two rounds. The table lists the rounds whose terms are confirmed by the company or by a named publication.
| Date | Round | Amount | Valuation | Leads | Source |
|---|---|---|---|---|---|
| April 21, 2022 | Series C | $350M equity plus credit facilities of up to $155M | $1.75B (reported by The Information) | G2 Venture Partners | Crunchbase News |
| December 12, 2024 | Series D | $600M | $2.8B | Founders Fund | Crusoe |
| October 2025 | Series E, initial close | $1.375B anticipated | More than $10B (expected) | Valor Equity Partners, Mubadala Capital | Crusoe |
| Late 2025 | Employee share sale | About $120M | About $13B (reported by The Information) | — | ION Analytics |
| September 17, 2026 | Series F, initial close | $3.9B anticipated, $3.1B sold per Form D | $30.9B post-money | Atreides Management, Mubadala Capital, Valor Equity Partners | Crusoe, SEC |
Earlier seed, Series A and Series B rounds are left out: we found no primary source for their terms. The employee share sale is not a funding round, and its valuation is known only from press reports.
From the Series C to the Series F the valuation rose about 18 times; from the Series E it roughly tripled in less than a year. The Series F terms imply a pre-money valuation of about $27 billion ($30.9 billion minus $3.9 billion, our calculation). The Form D notes that the amounts sold include certain previously issued SAFEs (simple agreements for future equity). Besides the three leads, Founders Fund, GIC, NVIDIA, the Qatar Investment Authority, Radical Ventures and TPG took part. How to read round sizes and stages is explained in Series A, B, C and D rounds.
Why did Crusoe's valuation triple in 2026?
Investors priced in contracted capacity: between the Series E and the Series F, Crusoe signed new campuses with large technology companies and a large multi-year cloud contract.
The round took six months to come together. In March 2026, Axios Pro reported a target of up to $2 billion at a valuation of $30–40 billion (see our March report). In July, Bloomberg reported talks on about $3 billion at roughly $30 billion, and on September 3 it reported that more than $3 billion had been raised at about that level (our September report). The official terms, $30.9 billion post-money, landed near the low end of the range discussed in the spring.
Over the same months the backlog the company discloses grew. In June 2026 Crusoe reported 4.9 GW under contract and a pipeline of more than 40 GW. On September 17 it reported more than 6 GW under contract, 1 GW delivered and operational, total contracted value above $140 billion, Crusoe Cloud bookings for the year to date up more than 20 times year over year and more than $100 million of contracted annual recurring revenue in managed inference.
New deals in 2026 included a 900 MW campus in Abilene for Microsoft, announced in March, and a 1 GW campus with Lancium in Childress, Texas. According to Bloomberg, as reported by TechCrunch, Crusoe also signed a five-year cloud contract worth about $13 billion with the trading firm Jane Street; neither company has disclosed its terms.
What is known about Crusoe's revenue?
Only estimates and company forecasts reported by the press. Crusoe is private and publishes no audited results.
- 2024: about $250 million, according to The Information, as relayed by The Logic in August 2025. Research firm Sacra estimates $276 million.
- 2025: the company projected about $500 million, according to the same reporting. Actual results have not been published.
- 2026: the company's projection was about $2.2 billion, according to The Information. It was made in 2025, before most of the new contracts.
- What Crusoe discloses itself: contracted capacity, operating capacity, total contracted value and growth rates, not revenue.
Total contracted value of $140 billion is not revenue. It covers multi-year contracts and turns into revenue over their term, as the capacity is delivered. Why this distinction matters when assessing a late-stage company is covered in how to evaluate pre-IPO companies.
What role do Stargate and Abilene play?
Abilene is Crusoe's flagship and its main proof of execution: a 1.2 GW campus built for Oracle and used by OpenAI as the lead site of the Stargate program.
OpenAI and SoftBank announced Stargate in January 2025 as a plan to invest $500 billion in US AI infrastructure over four years, with SoftBank, OpenAI, Oracle and MGX as the initial equity funders and the buildout starting in Texas. Crusoe develops the Abilene campus with Lancium: eight buildings and about 4 million square feet, each building designed, according to Crusoe, to run up to 50,000 NVIDIA GB200 NVL72s on a single network fabric. The first phase went live in 2025; in June 2026 Crusoe said two buildings were operating and six were under construction.
The 900 MW campus for Microsoft sits next to it and brings the projected capacity of the Abilene site to 2.1 GW, with the first building expected to be energized in mid-2027. In September 2026 Crusoe also disclosed that it is developing a campus for Google in Armstrong County, Texas. Not every project goes ahead: in June 2026 Crusoe paused development of a planned 1.8 GW campus near Cheyenne, Wyoming, at its customer's request.
How does Crusoe compare with CoreWeave?
CoreWeave is the closest listed peer and the reference point for pricing GPU clouds; Crusoe differs by also developing sites and sourcing power.
CoreWeave priced its IPO on March 27, 2025, at $40 a share, selling 37.5 million shares for about $1.5 billion, and began trading on Nasdaq the next day. By early December 2025 its shares were 113% above their debut price, ION Analytics noted. Lambda, another GPU cloud provider, had hired banks for a possible listing, the same report said.
Crusoe's difference is vertical integration. It finds the power, builds the campus and runs the cloud, which gives it more control over timing and cost but also adds construction and energy risk that a pure cloud operator does not carry. All of these companies compete for the same customers and the same NVIDIA hardware.
When could Crusoe go public?
No date has been set. As of October 21, 2026, Crusoe has not publicly filed a registration statement, although it has held talks with banks.
ION Analytics reported in December 2025 that Crusoe was discussing a listing as early as 2026, with no lead bank appointed. In August 2026 Axios Pro reported talks with JPMorgan, Goldman Sachs, Morgan Stanley and Bank of America, and in September TechCrunch wrote that the company had recently met investment bankers, including Goldman Sachs and Morgan Stanley, to discuss a potential IPO. SEC EDGAR lists only Form D notices for Crusoe Inc.; a confidential draft registration would not appear there.
Crusoe has also strengthened its management and board. In December 2025 it hired Michael Gordon, MongoDB's former chief financial officer and chief operating officer, who led MongoDB through its IPO, as COO and CFO. In September 2026 it added three board members, including Cloudflare CFO Thomas Seifert.
What are the risks?
The main risks are dependence on a few very large customers, heavy capital needs, limited disclosure and the illiquidity of private shares.
- Customer concentration. Gigawatt campuses are built for a handful of tenants such as Oracle, Microsoft and Google. A customer can change plans, as the Wyoming pause in June 2026 showed.
- Capital and execution. Each campus needs billions of dollars of equity and debt before it earns revenue, and construction delays push revenue back.
- Limited disclosure. Revenue figures are estimates and forecasts, and contracted value is not recognized revenue.
- Valuation. $30.9 billion is the price of a private round with negotiated terms, not a market price; a later round or an IPO can be priced lower.
- Competition. Hyperscalers and other GPU clouds compete for the same customers, chips and power.
- Liquidity. Until a listing, Crusoe shares change hands only in private transactions that the company can restrict; see how private market liquidity differs.
Frequently asked questions
What is Crusoe's latest valuation?
$30.9 billion post-money, the valuation of its Series F, whose initial close Crusoe announced on September 17, 2026. The round targets $3.9 billion.
Has Crusoe filed for an IPO?
No. As of October 21, 2026, SEC EDGAR lists only Form D notices for Crusoe, although the company has held talks with banks about a listing.
Does Crusoe disclose its revenue?
No. Crusoe is private and does not publish audited results; reported figures, such as about $250 million for 2024, are estimates from The Information.
Source: Crusoe September 17, 2026
Stay ahead of the market
Get the latest venture capital and investment insights delivered to your inbox.